by Andy Huffman | Jul 20, 2026 | Storm Damage & Insurance
My Roof Insurance Claim Was Denied — What Do I Do Now?
A denied roof insurance claim is frustrating — but it’s not necessarily the end of the road. Denials and underpayments can be successfully appealed, and many homeowners who give up after an initial denial would have received coverage with proper follow-through.
Here’s exactly what to do.
Step 1 — Get the Denial in Writing
If your claim was denied verbally or by phone, request a written denial letter that includes:
– The specific reason for denial
– The exact policy language being cited as the basis for denial
– The claim number and adjuster’s contact information
Insurance companies are required to provide written explanation of claim decisions. This documentation is essential for your appeal.
Step 2 — Understand Why It Was Denied
The most common reasons for roof insurance claim denials:
“Normal wear and tear” — The most common denial reason. Adjusters sometimes classify storm damage as age-related deterioration to avoid coverage. The critical question: was there a specific storm event that caused or accelerated this damage? If yes, this classification may be incorrect.
“Pre-existing damage” — The insurer claims the damage predates your policy or a specific storm event. Countered by: professional documentation of when damage occurred, weather service records for storm dates, and documentation of your roof’s pre-storm condition.
“Maintenance issue” — The insurer claims the damage resulted from lack of maintenance rather than a covered event. Countered by: documentation showing regular maintenance and that the damage pattern is consistent with storm events rather than neglect.
“Outside coverage scope” — Flood damage (requires separate flood policy), damage from tree roots, or gradual deterioration may be genuinely outside coverage. Review your policy carefully.
“Claim filed outside policy period” — Most policies have reporting requirements. If you delayed filing, this may be a legitimate denial basis — though exceptions exist for damage that wasn’t reasonably discoverable.
Step 3 — Get a Second Professional Inspection
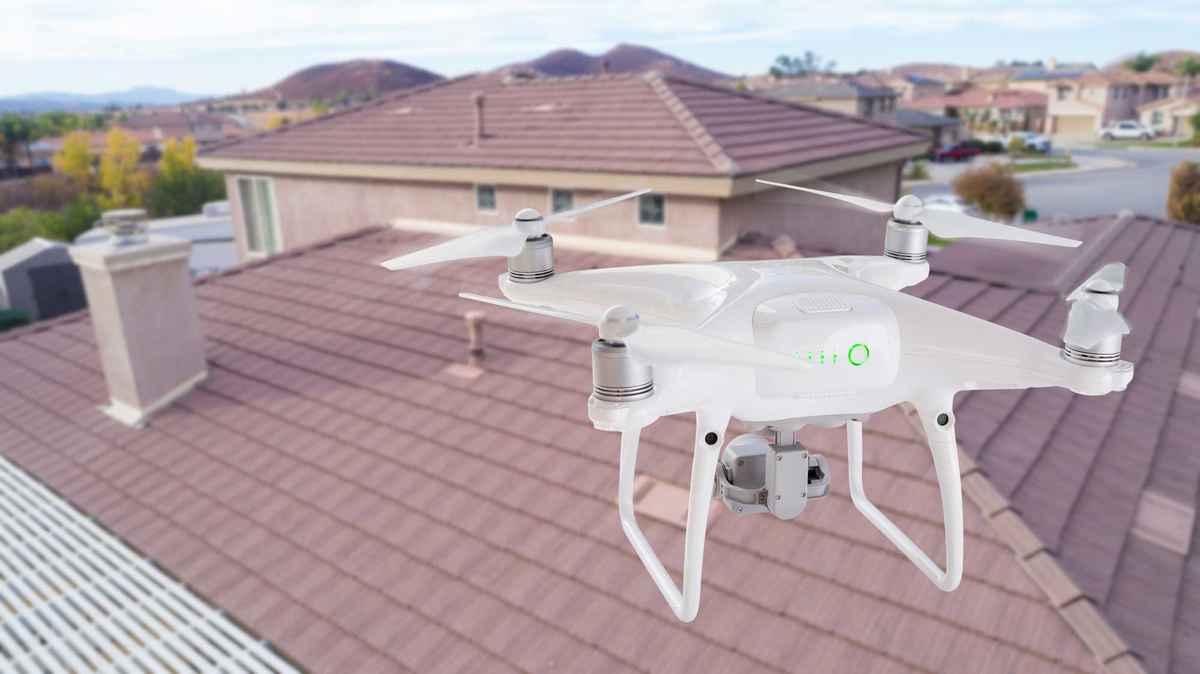
If you don’t already have a contractor’s independent damage assessment, get one now. An Alamo drone inspection provides:
– High-resolution photographic documentation of all damage
– Written report identifying damage consistent with storm events
– Professional assessment contradicting an “age/wear” determination where appropriate
– Documentation formatted for insurance appeal use
Our inspection is free and specifically designed to produce usable insurance claim documentation.
Step 4 — File a Formal Appeal
Every insurance policy has an appeal or reconsideration process. With your written denial, contractor’s report, and supporting documentation:
- Request re-inspection — Ask your insurer to send a different adjuster for a second look, with your contractor’s documentation in hand
- Submit formal appeal — Send a written appeal to the claims department (not just your adjuster) with all supporting documentation
- Invoke the appraisal provision — Most homeowners policies include an appraisal clause allowing both parties to hire independent appraisers, with a neutral umpire deciding disputes
Step 5 — File a State Department of Insurance Complaint
If your insurer is acting in bad faith or refusing to respond reasonably to a valid appeal, file a formal complaint with your state’s insurance regulator:
Indiana Department of Insurance:
(317) 232-2385 | in.gov/idoi
Illinois Department of Insurance:
(217) 782-4515 | insurance.illinois.gov
State insurance department complaints go on the insurer’s permanent regulatory record. Insurance companies take these complaints seriously.
Step 6 — Consider a Public Adjuster
Public adjusters are licensed professionals who represent policyholders (not insurers) in claim negotiations. They typically charge 10-15% of the final settlement as their fee.
For large denied claims where significant money is at stake, a public adjuster’s expertise can be worth their fee — particularly in complex disputes.
What Alamo Does at No Charge
We help our customers with:
– Free professional damage documentation for initial claims and appeals
– Supplemental claim preparation if the initial payout is inadequate
– Written contractor letters supporting storm-related damage assessment
– Guidance on the appeal process based on our experience with hundreds of Indiana and Illinois claims
We don’t charge for any of this — we get paid when we do roofing work, and a fair claim settlement is what makes our work possible.
If your claim was denied or underpaid, call (219) 224-2636. We’ll review your situation and tell you honestly what options you have.
About Alamo Roofing Contractors
Alamo Roofing Contractors is a GAF Master Elite certified roofing contractor serving Northwest Indiana and northern Illinois since 2017. Based in Portage, Indiana at 6064 Lute Rd, we serve Lake County, Porter County, LaPorte County, Cook County, Will County, and DuPage County with residential and commercial roofing, siding, gutters, and exterior services.
[Schedule Your Free Estimate] → https://api.leadconnectorhq.com/widget/booking/DKc0HhICa64zXLn8XJtX
[Call (219) 224-2636] → tel:+12192242636
Mon–Fri 9AM–5PM | Sat 9AM–3PM | 24/7 Emergency Storm Response
by Andy Huffman | Jul 9, 2026 | Storm Damage & Insurance
How to Read Your Insurance Adjuster’s Roof Report — A Line-by-Line Guide
When your insurance adjuster’s report arrives, most homeowners look at the bottom line and assume that’s their settlement. It isn’t — it’s a starting point, and it’s often incomplete.
Understanding how to read the scope of damage document can mean the difference between a fair settlement and leaving $2,000-$8,000 on the table.
What the Report Actually Is
The adjuster’s report — called a “scope of damage” or “estimate” — is an itemized list of what the insurance company believes needs to be repaired or replaced, at what price. It’s generated using estimating software (most commonly Xactimate) that prices each item using regional labor and material rates.
The report is not final. It’s the insurance company’s opening position.
The Key Sections to Understand
Line items: Each element of your roof is listed separately — shingles by the square, underlayment, ice and water shield, ridge cap, starter strips, flashing, drip edge, ventilation, etc.
RCV (Replacement Cost Value): What the full replacement of each item costs at today’s prices.
Depreciation: The amount deducted from RCV to calculate ACV (actual cash value) based on age and condition.
ACV (Actual Cash Value): RCV minus depreciation — what you receive in your first check.
Recoverable depreciation: The difference between RCV and ACV — what you receive after completing repairs (RCV policies only).
Deductible: Subtracted from the ACV to calculate your first payment.
What’s Commonly Missing from Adjuster Reports
Adjusters working quickly under high caseloads (especially after major storm events) frequently miss or undervalue these items. Compare the adjuster’s line items against your contractor’s estimate:
Ice and water shield: Often listed at minimum code coverage (2 feet from edge). Many replacement projects in Lake County and Porter County require more extensive application — especially on homes with low pitches or documented ice dam history.
Starter strip shingles: Sometimes omitted or priced at shingle cost rather than the correct specialty product cost.
Ridge cap shingles: Occasionally omitted entirely or priced at standard shingle rates rather than ridge cap rates.
Drip edge: Frequently omitted in older reports, especially on homes that didn’t have it originally — but current building code requires it on replacement projects.
Pipe boot replacement: Often only included if the inspector physically saw each boot. Drone inspections catch deteriorated boots that ground-level inspectors miss.
Detach and reset (D&R) for satellite dishes, vents, and skylights: If anything needs to be removed and reinstalled to complete the roofing work, it should be in the estimate.
Code upgrade allowances: Current Indiana and Illinois building codes may require upgrades (ventilation, drip edge, etc.) that weren’t present on the original roof. These code-required upgrades should be covered by insurance.
Overhead and profit (O&P): On projects requiring a general contractor to coordinate subcontractors, overhead and profit (typically 10% overhead + 10% profit) should be included. This is often disputed — Alamo helps with O&P claims.
How to Submit a Supplement
If your contractor’s estimate is higher than the adjuster’s estimate, you file a “supplement” — a formal request for additional payment with supporting documentation.
A successful supplement includes:
– Specific line-by-line comparison showing what’s missing or underpriced
– Photos documenting each supplemented item
– Code citations for required items
– Contractor’s signed estimate
Alamo Roofing prepares and submits supplemental claims for our customers at no charge. We know what adjusters look for and how to document supplements effectively.
What Happens If Your Claim Is Underpaid or Denied
If underpaid: Submit a supplement as described above. Most underpaid claims are resolved at this stage.
If denied: Request the denial in writing with specific policy language cited. Review the denial language carefully. You can request a re-inspection with a different adjuster, file an appeal within your policy’s process, or contact the Indiana Department of Insurance (317) 232-2385 or Illinois Department of Insurance (217) 782-4515.
Call (219) 224-2636 if you need help reviewing your adjuster’s report.
About Alamo Roofing Contractors
Alamo Roofing Contractors is a GAF Master Elite certified roofing contractor serving Northwest Indiana and northern Illinois since 2017. Based in Portage, Indiana, we serve Lake County, Porter County, LaPorte County, Cook County, Will County, and DuPage County.
[Schedule Your Free Estimate] → https://api.leadconnectorhq.com/widget/booking/DKc0HhICa64zXLn8XJtX
[Call (219) 224-2636] → tel:+12192242636
Mon–Fri 9AM–5PM | Sat 9AM–3PM | 24/7 Emergency Storm Response
by Andy Huffman | Jul 9, 2026 | Storm Damage & Insurance
When your insurance adjuster’s report arrives, most homeowners look at the bottom line and assume that’s their settlement. It isn’t — it’s a starting point, and it’s often incomplete.
Understanding how to read the scope of damage document can mean the difference between a fair settlement and leaving $2,000-$8,000 on the table.
What the Report Actually Is
The adjuster’s report — called a “scope of damage” or “estimate” — is an itemized list of what the insurance company believes needs to be repaired or replaced, at what price. It’s generated using estimating software (most commonly Xactimate) that prices each item using regional labor and material rates.
The report is not final. It’s the insurance company’s opening position.
Professional inspection ensures no damage goes undetected
The Key Sections to Understand
Line items: Each element of your roof is listed separately — shingles by the square, underlayment, ice and water shield, ridge cap, starter strips, flashing, drip edge, ventilation, etc.
RCV (Replacement Cost Value): What the full replacement of each item costs at today’s prices.
Depreciation: The amount deducted from RCV to calculate ACV (actual cash value) based on age and condition.
ACV (Actual Cash Value): RCV minus depreciation — what you receive in your first check.
Recoverable depreciation: The difference between RCV and ACV — what you receive after completing repairs (RCV policies only).
Deductible: Subtracted from the ACV to calculate your first payment.
Quality materials and expert installation make the difference
What’s Commonly Missing from Adjuster Reports
Adjusters working quickly under high caseloads (especially after major storm events) frequently miss or undervalue these items. Compare the adjuster’s line items against your contractor’s estimate:
Ice and water shield: Often listed at minimum code coverage (2 feet from edge). Many replacement projects in Lake County and Porter County require more extensive application — especially on homes with low pitches or documented ice dam history.
💡 Pro Tip
Schedule a professional inspection within 30 days of any major storm. Early detection prevents costly repairs down the road.
Starter strip shingles: Sometimes omitted or priced at shingle cost rather than the correct specialty product cost.
Ridge cap shingles: Occasionally omitted entirely or priced at standard shingle rates rather than ridge cap rates.
Drip edge: Frequently omitted in older reports, especially on homes that didn’t have it originally — but current building code requires it on replacement projects.
Pipe boot replacement: Often only included if the inspector physically saw each boot. Drone inspections catch deteriorated boots that ground-level inspectors miss.
Detach and reset (D&R) for satellite dishes, vents, and skylights: If anything needs to be removed and reinstalled to complete the roofing work, it should be in the estimate.
Code upgrade allowances: Current Indiana and Illinois building codes may require upgrades (ventilation, drip edge, etc.) that weren’t present on the original roof. These code-required upgrades should be covered by insurance.
Overhead and profit (O&P): On projects requiring a general contractor to coordinate subcontractors, overhead and profit (typically 10% overhead + 10% profit) should be included. This is often disputed — Alamo helps with O&P claims.
Alamo Roofing serves Lake County, Porter County & northern Illinois
How to Submit a Supplement
If your contractor’s estimate is higher than the adjuster’s estimate, you file a “supplement” — a formal request for additional payment with supporting documentation.
A successful supplement includes:
- Specific line-by-line comparison showing what’s missing or underpriced
- Photos documenting each supplemented item
- Code citations for required items
- Contractor’s signed estimate
Alamo Roofing prepares and submits supplemental claims for our customers at no charge. We know what adjusters look for and how to document supplements effectively.
What Happens If Your Claim Is Underpaid or Denied
If underpaid: Submit a supplement as described above. Most underpaid claims are resolved at this stage.
If denied: Request the denial in writing with specific policy language cited. Review the denial language carefully. You can request a re-inspection with a different adjuster, file an appeal within your policy’s process, or contact the Indiana Department of Insurance (317) 232-2385 or Illinois Department of Insurance (217) 782-4515.
Ready for Your Free Roof Inspection?
Call us at (219) 248-2194 or book online below.
Mon–Fri 9AM–5PM | Sat 9AM–3PM | 24/7 Emergency Storm Response
Schedule Your Free Roof Inspection
Get Your Free Roof Inspection
Free drone inspections across Lake County, Porter County & northern Illinois. Honest assessments — repair, replace, or no action needed.
(219) 248-2194
Book Online
Mon–Fri 9AM–5PM · Sat 9AM–3PM · 24/7 Emergency Storm Response
Schedule Your Free Roof Inspection
by Andy Huffman | Jun 11, 2026 | Storm Damage & Insurance
Emergency Roof Repair — What to Do When Your Roof Is Actively Leaking
An actively leaking roof is a home emergency. Water entering your home causes damage that compounds quickly — wet insulation, mold growth, damaged drywall, and in severe cases structural damage. Acting quickly and correctly minimizes the damage.
Here’s exactly what to do.
In the First 30 Minutes
1. Protect your interior first.
Move furniture and belongings away from the leak area. Place buckets, pots, or trash cans to catch active dripping. Lay plastic sheeting or tarps on floors and furniture that can’t be moved. If water is reaching electrical fixtures or outlets, turn off the circuit breaker for that area and do not use those outlets until the situation is resolved.
2. Contain the water source if you can safely reach it.
If water is pooling on your ceiling and the ceiling is sagging, the pooled water is putting pressure on the drywall that could cause a sudden failure. Create a small hole in the lowest point of the bulge to allow controlled drainage rather than a sudden collapse. This sounds counterintuitive but prevents larger damage.
3. Document everything.
Take photos and video of all interior water damage — ceiling, walls, flooring, affected belongings. This documentation is critical for your insurance claim. Time-stamp everything.
4. Call Alamo at (219) 224-2636 — 24/7 emergency response.
We serve Lake County, Porter County, and northern Illinois with 24/7 emergency response. We can reach most of our service area within 30-60 minutes and provide emergency tarping to stop water entry while permanent repairs are planned.
What NOT to Do
Do not climb on a wet roof. This is the most important safety point. Wet roofs — especially after rain or during a storm — are extremely dangerous. Roofing professionals use specific fall protection equipment. Homeowners attempting to get on a wet roof sustain serious injuries every year.
Do not attempt permanent repairs in dangerous conditions. Emergency tarping to stop water entry is appropriate. Attempting to nail down shingles or seal flashing during active rain or on a slippery surface is not.
Do not use a shop vac on ceiling water without checking for electrical hazards. If the area near the leak has any electrical components, treat the water as potentially electrically charged until the circuit is confirmed off.
Emergency Tarping — What It Is and When It’s Needed
Emergency tarping involves covering the compromised area of your roof with heavy-duty poly tarps weighted and secured to prevent wind lift. It’s a temporary measure — not a repair — but it stops water infiltration while permanent repairs are planned and scheduled.
When tarping is appropriate:
– Active leak with significant water entry
– Storm-related damage that creates a large opening
– Fallen tree or limb through the roof
– Major shingle blow-off exposing the deck
Keep receipts for any emergency tarping materials you purchase — these costs are typically reimbursable under your homeowners insurance as necessary mitigation expenses.
After the Emergency — Next Steps
Once the immediate water entry is controlled:
- Contact your insurance company to open a claim. Get a claim number.
- Schedule a professional damage assessment — Alamo will document all damage with drone photography for your insurance claim.
- Get permanent repair or replacement scheduled — we’ll provide a written estimate and work with your adjuster.
How Fast Can Alamo Respond?
From our Portage, Indiana base:
– Crown Point, Schererville, Munster, Hammond, Hobart, Portage: 15-25 minutes
– Valparaiso, Chesterton, Michigan City: 25-45 minutes
– Lansing, South Holland, Chicago Heights, Oak Lawn: 30-45 minutes
– New Lenox, Mokena, Joliet, Lockport: 45-60 minutes
For a roofing emergency, call (219) 224-2636 any time — day or night.
About Alamo Roofing Contractors
Alamo Roofing Contractors is a GAF Master Elite certified roofing contractor serving Northwest Indiana and northern Illinois since 2017. Based in Portage, Indiana, we serve Lake County, Porter County, LaPorte County, Cook County, Will County, and DuPage County.
[Schedule Your Free Estimate] → https://api.leadconnectorhq.com/widget/booking/DKc0HhICa64zXLn8XJtX
[Call (219) 224-2636] → tel:+12192242636
Mon–Fri 9AM–5PM | Sat 9AM–3PM | 24/7 Emergency Storm Response